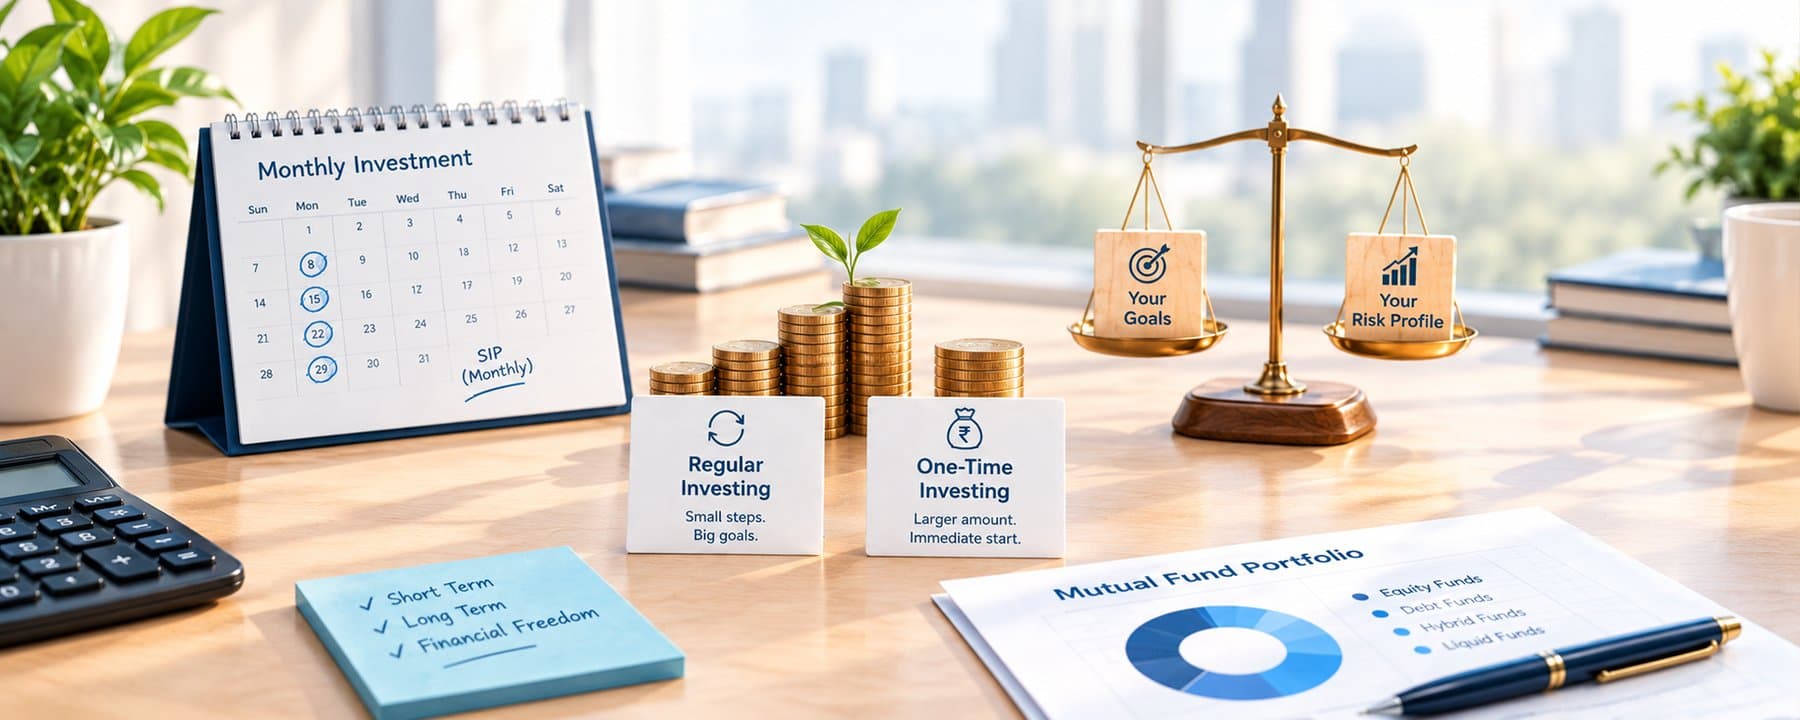
When you decide to invest in mutual funds, one of the first questions is often simple: should you invest a fixed amount regularly through a SIP, or invest a larger amount at once as a lump sum?
Both approaches can help you build wealth, but they work differently. A SIP spreads your investment across time, while a lump-sum investment puts your capital into the market in one go. The better approach depends on your cash flow, market comfort, financial goals and investment horizon.
For many investors, the decision is not about choosing one permanently over the other. It is about understanding when each approach may be more suitable.
Key Takeaways
- A SIP allows you to invest a fixed amount at regular intervals, usually monthly.
- A lump-sum investment involves investing a larger amount at one time.
- SIPs can help reduce the pressure of timing the market because investments are spread across different market levels.
- Lump-sum investing gives your entire capital market exposure from the beginning.
- Neither approach guarantees better returns.
- Your income pattern, available capital, risk tolerance and investment horizon should guide the decision.
What Is a SIP?
A Systematic Investment Plan, or SIP, allows you to invest a fixed amount in a mutual fund at regular intervals.
For example, instead of investing ₹1,20,000 at once, you may choose to invest ₹10,000 every month for 12 months.
Each SIP instalment buys mutual fund units at the prevailing Net Asset Value, or NAV. When markets fall, the same investment amount may buy more units. When markets rise, it may buy fewer units.
This regular investment process is commonly associated with rupee cost averaging.
What Is a Lump-Sum Investment?
A lump-sum investment means investing a larger amount in one transaction rather than spreading it across multiple instalments.
For example, if you receive a ₹5 lakh bonus and invest the entire amount into a mutual fund at once, it would be considered a lump-sum investment.
Your full capital begins participating in market movements from the date of investment.
This can work differently from a SIP because the timing of the initial investment has a greater impact on short-term performance.
How Does a SIP Work?
Suppose you invest ₹5,000 every month in an equity mutual fund.
Your investments may look like this:
| Month | SIP Amount | NAV | Units Purchased |
|---|---|---|---|
| Month 1 | ₹5,000 | ₹50 | 100 |
| Month 2 | ₹5,000 | ₹40 | 125 |
| Month 3 | ₹5,000 | ₹50 | 100 |
| Month 4 | ₹5,000 | ₹62.50 | 80 |
When NAV falls, your fixed SIP amount buys more units. When NAV rises, you buy fewer units.
Over time, this can average your acquisition cost across different market conditions.
However, rupee cost averaging does not eliminate investment risk or guarantee higher returns.
How Does Lump-Sum Investing Work?
Suppose you have ₹2 lakh available today and decide to invest the entire amount in an equity mutual fund.
If the NAV is ₹50, you receive:
₹2,00,000 ÷ ₹50 = 4,000 units
Your full ₹2 lakh is invested from day one.
If markets rise afterwards, the entire investment participates in that growth. If markets fall soon after, the full investment also experiences that decline.
This is why lump-sum investing may involve greater sensitivity to entry timing, particularly over shorter periods.
SIP vs Lump Sum: Key Differences
| Factor | SIP | Lump Sum |
|---|---|---|
| Investment Style | Regular instalments | One-time investment |
| Capital Required Initially | Relatively smaller | Larger amount |
| Market Timing Impact | Spread across multiple entry points | Greater impact from initial entry point |
| Cash-Flow Suitability | Regular income | Available surplus capital |
| Investment Discipline | Automated and regular | Depends more on investor decision |
| Market Volatility | Investment spread over time | Entire amount exposed immediately |
| Long-Term Compounding | Builds gradually | Entire capital compounds from the beginning |
Neither structure is automatically superior. Their suitability depends on the investor's circumstances.
What Are the Benefits of Investing Through SIPs?
Builds Investment Discipline
SIPs can help create a regular investing habit.
If investments are automated every month, you may be less likely to postpone investing because of short-term market uncertainty.
Suitable for Regular Income
For salaried investors or individuals with predictable monthly cash flow, SIPs allow investing to happen alongside monthly income.
You do not need to accumulate a large amount before starting.
Reduces Pressure to Time the Market
Predicting market highs and lows consistently is difficult.
With a SIP, your investments occur across different market conditions, reducing the dependence on a single entry point.
Can Support Goal-Based Investing
A SIP can be linked to specific goals such as:
- retirement;
- child's education;
- home purchase;
- long-term wealth creation; or
- other future milestones.
This makes it easier to connect regular investing with a defined financial objective.
What Are the Limitations of SIPs?
SIPs also have limitations.
If markets rise continuously, money invested later may enter at progressively higher prices. In such a scenario, an earlier lump-sum investment could have had more capital exposed to the rising market.
SIPs also do not protect against losses. If the value of the underlying mutual fund declines, your investment can still fall.
The main advantage of SIP is disciplined and staggered investing, not guaranteed safety.
What Are the Benefits of Lump-Sum Investing?
Full Capital Starts Working Immediately
When you invest a lump sum, the entire amount enters the market at once.
If your investment horizon is long and the market performs favourably over time, the full amount gets the benefit of compounding from the beginning.
Useful for Investors With Surplus Funds
Lump-sum investing may be relevant if you receive:
- a bonus;
- maturity proceeds;
- inheritance;
- business surplus;
- sale proceeds from an asset; or
- another large inflow.
Instead of leaving the amount idle, you may choose to invest based on your goals and risk profile.
Simpler to Manage
A one-time investment requires fewer transactions and may be easier for investors who already have a clear asset-allocation plan.
What Are the Risks of Lump-Sum Investing?
The biggest risk is timing.
If you invest a large amount shortly before a significant market decline, the portfolio may experience a sharp short-term fall.
For an investor who is uncomfortable with volatility, this can lead to emotional decisions such as redeeming too early.
Lump-sum investing may therefore require:
- a long enough investment horizon;
- higher tolerance for market fluctuations; and
- confidence that the money will not be required soon.
Which Approach May Suit Salaried Investors?
For many salaried investors, SIPs can be convenient because income is received regularly.
A monthly SIP allows a portion of salary to be invested automatically before it is spent elsewhere.
For example, if you earn every month and want to invest ₹8,000 toward retirement, setting up a monthly SIP may be more practical than waiting to accumulate ₹96,000 at the end of the year.
The consistency can matter more than trying to identify the “perfect” market level.
When Can Lump-Sum Investing Make Sense?
A lump-sum approach may be considered when:
- you already have a large investible surplus;
- your emergency fund is in place;
- you have no immediate need for the money;
- your investment horizon is sufficiently long;
- the investment matches your asset-allocation plan; and
- you are comfortable with short-term market fluctuations.
The decision should not be based only on whether the market currently appears “cheap” or “expensive”.
What if You Have a Large Amount but Are Worried About Market Timing?
Some investors have a large amount available but may not feel comfortable investing the entire sum immediately.
In such cases, they may choose to stagger investments over several months.
One possible approach is to temporarily hold the amount in a lower-volatility instrument and transfer it gradually into the target mutual fund.
This can reduce the emotional pressure of entering the market on a single day, although it may also mean that part of the money remains out of the target investment for longer.
SIP vs Lump Sum During a Market Fall
A market decline affects the two approaches differently.
With a SIP, future instalments continue buying units at lower NAVs if the market falls.
With a lump sum, the entire amount may decline in value soon after investment.
However, this does not mean SIPs always outperform during volatile periods. Future market movements and the length of the investment period still matter.
The more useful question is whether your chosen approach helps you remain invested without reacting emotionally to short-term volatility.
Can You Use SIP and Lump Sum Together?
Yes.
SIP and lump sum do not have to be treated as mutually exclusive strategies.
An investor may:
- continue regular SIPs from monthly income;
- invest bonuses as lump sums;
- increase SIPs when income rises; and
- deploy additional surplus when suitable.
This hybrid approach can be practical because it uses both regular cash flow and occasional surplus capital.
Which Approach Is Better for Long-Term Goals?
For long-term goals, consistency and staying invested generally matter more than choosing between SIP and lump sum in isolation.
A SIP may suit someone who builds the corpus gradually through regular income.
A lump sum may suit someone who already has capital available and is willing to invest it for a long period.
The key factors remain:
- required corpus;
- time available;
- expected contribution capacity;
- risk tolerance; and
- asset allocation.
How Should You Choose Between SIP and Lump Sum?
Before deciding, ask yourself the following questions:
Do I Have a Large Amount Available Today?
If not, a SIP may be the more practical route.
Is My Income Regular?
A SIP can align naturally with regular monthly income.
How Comfortable Am I With Market Volatility?
If investing a large amount at once would make you anxious during a market fall, staggered investing may be easier to maintain.
How Long Can I Stay Invested?
Longer investment horizons generally give market-linked investments more time to move through different market cycles.
Do I Already Have an Emergency Fund?
Money required for near-term expenses or emergencies should not usually be exposed to unnecessary market risk.
Common Mistakes to Avoid
Stopping SIPs During Every Market Fall
Market declines can be uncomfortable, but stopping investments purely because prices have fallen may work against the discipline a SIP is designed to create.
Investing a Lump Sum Without a Plan
A large bank balance does not automatically mean the entire amount should go into equities.
Asset allocation and liquidity needs should come first.
Waiting Forever for the Perfect Entry Point
Investors may keep money uninvested for months while waiting for markets to fall.
Market timing is difficult to execute consistently.
Comparing Only Short-Term Returns
A SIP and lump sum enter the market differently, so comparing them over a short period can be misleading.
The comparison should be made in the context of your actual investment horizon and goals.
Conclusion
SIP and lump-sum investing are two different ways of putting money to work.
A SIP may suit investors with regular income who want disciplined, staggered investing without relying heavily on market timing. Lump-sum investing may be suitable for investors who already have surplus capital and are comfortable investing it for a sufficiently long period.
Neither approach guarantees better returns. Your decision should be based on your cash flow, financial goals, risk tolerance, available capital and investment horizon.
In many cases, investors may use both approaches together rather than choosing only one.