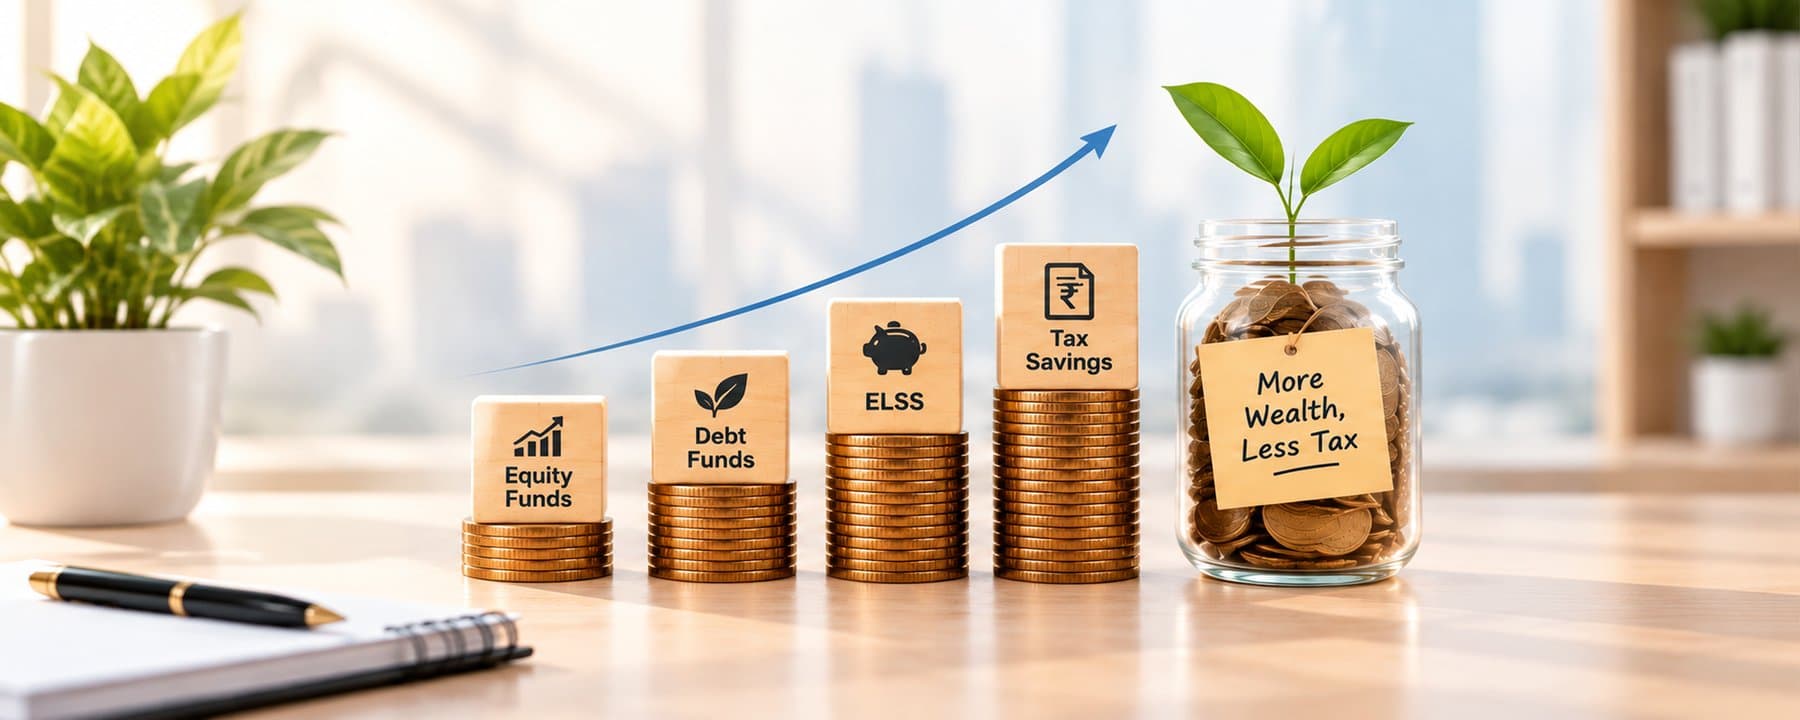
A strong investment return is only one part of wealth creation. What ultimately matters is how much of that return you are able to retain after taxes, charges and inflation.
Tax-efficient investing does not mean choosing an investment simply because it offers a deduction. It means understanding how different investments are taxed, when a tax liability may arise and how your investment decisions can be structured around your goals, holding period and tax regime.
For Indian investors, this has become especially important because tax treatment differs across equity, mutual funds, fixed-income products, retirement investments and other assets. The right approach is to consider both investment suitability and post-tax returns, rather than looking at tax benefits in isolation.
Key Takeaways
- Tax-efficient investing focuses on improving post-tax returns without compromising your financial goals.
- Your tax regime matters because many deductions available under the old regime are restricted under the new regime.
- Holding period can affect whether investment gains are treated as short-term or long-term.
- ELSS and certain retirement contributions can provide tax benefits, subject to the applicable regime and eligibility.
- Capital losses may be used to offset eligible capital gains and, subject to conditions, carried forward for up to eight years.
- Tax should influence an investment decision, but it should not be the only reason for choosing a product.
What Is Tax-Efficient Investing?
Tax-efficient investing is the process of structuring your investments in a way that reduces unnecessary tax outflows while remaining aligned with your financial goals.
For example, two investments may generate similar pre-tax returns but produce different post-tax outcomes because of differences in:
- tax rates;
- holding periods;
- deduction eligibility;
- interest or dividend taxation;
- capital-gains treatment; and
- withdrawal rules.
The aim is not to avoid tax. It is to understand how taxation affects your portfolio and make informed choices within the law.
Why Does Tax Efficiency Matter?
Taxes directly affect the amount of wealth that remains available for reinvestment or future goals.
Consider two investments generating the same gross return. If one creates frequent taxable income while the other allows more tax-efficient compounding, their long-term outcomes may differ even before considering risk.
Tax efficiency becomes particularly relevant for investors with:
- higher taxable income;
- multiple asset classes;
- long investment horizons;
- retirement goals;
- regular portfolio rebalancing; or
- large realised capital gains.
Start by Understanding Your Tax Regime
The first step is knowing whether you are using the old tax regime or the new tax regime.
The new regime is the default for eligible taxpayers, although eligible individuals may opt for the old regime subject to applicable rules. The old regime allows several deductions and exemptions, while many Chapter VI-A deductions are generally unavailable under the new regime, except specified deductions such as eligible employer contributions to pension schemes.
This matters because a tax-saving investment may be useful under one regime but provide little or no additional deduction under another.
Before investing for tax purposes, ask:
- Which tax regime applies to me?
- Am I actually eligible for the deduction?
- Does the investment also fit my goals?
- What are the lock-in and withdrawal conditions?
Understand How Capital Gains Are Taxed
When you sell or redeem an investment for more than its cost, the profit may be taxed as a capital gain.
The tax treatment can depend on:
- the type of asset;
- how long you held it;
- whether it is listed or unlisted;
- whether securities transaction tax conditions apply; and
- current tax rules.
For listed equity shares and equity-oriented mutual funds, the holding period is generally important in determining whether a gain is treated as short-term or long-term. The Income Tax Department recognises a 12-month holding-period threshold for several listed securities and equity-oriented mutual funds.
The Department also currently recognises an exemption threshold of ₹1.25 lakh for eligible long-term capital gains under the relevant equity-capital-gains provisions.
Because capital-gains rules can change, investors should verify the rates applicable to the relevant tax year before selling.
Avoid Unnecessary Churning
Frequent buying and selling can create repeated taxable events.
Even when portfolio changes appear profitable before tax, frequent realisation of gains can reduce the amount left to compound.
This does not mean you should never sell. Rebalancing, risk reduction or exiting an unsuitable investment can be valid reasons.
The key is to avoid unnecessary portfolio turnover driven only by short-term market movements.
Consider Tax-Loss Harvesting Carefully
Tax-loss harvesting involves selling an investment that is trading below its purchase price and using the realised loss to offset eligible capital gains.
Under current rules, short-term capital losses may generally be adjusted against both short-term and long-term capital gains, while long-term capital losses may generally be adjusted only against long-term capital gains. Eligible unabsorbed capital losses can also be carried forward for up to eight years, subject to filing requirements.
For example, suppose you have:
- ₹80,000 in realised short-term capital gains; and
- ₹30,000 in an investment loss that you choose to realise.
Subject to applicable tax rules, the loss may reduce the taxable capital gain.
However, tax-loss harvesting should not become a reason to sell a fundamentally suitable investment without considering the broader portfolio impact.
Use Tax-Saving Investments Only When They Fit Your Goals
Some investment products provide deductions under the old tax regime.
ELSS
Equity Linked Savings Schemes are equity-oriented mutual funds that qualify within the overall tax-saving framework available under the old regime.
The broader specified-savings deduction limit remains ₹1.5 lakh for eligible taxpayers.
ELSS can be relevant for investors who:
- are using the old tax regime;
- are comfortable with equity-market risk;
- have a long-term investment horizon; and
- want tax saving alongside equity exposure.
However, tax benefits alone should not determine whether an equity product is suitable.
NPS
The National Pension System can also offer tax benefits, subject to applicable rules.
Historically, eligible individual contributions could qualify for an additional deduction of up to ₹50,000 under the relevant pension provision in the old regime. Current tax-year applicability should be checked before investing.
NPS may be more suitable when retirement planning is the primary goal rather than short-term tax saving.
Think About Interest and Dividend Income
Not all investment returns are taxed as capital gains.
Interest from deposits and several fixed-income instruments is generally treated as income and may be taxed at the applicable rate, depending on the product and investor profile.
Dividend income is also reported as income from other sources and is generally subject to the applicable tax treatment.
This is why comparing only the headline return can be misleading.
For example, a fixed-income product offering 7.5% before tax may produce a lower effective return for an investor in a higher tax bracket.
Always compare post-tax return, not just stated return.
Match Investments With the Right Time Horizon
Holding an investment for an appropriate period can improve both investment discipline and tax efficiency.
Short-term goals generally require stability and liquidity. Long-term goals can often tolerate greater market volatility and may benefit more from compounding.
When evaluating tax efficiency, consider:
| Question | Why It Matters |
|---|---|
| How long will I remain invested? | Holding period can affect tax treatment |
| Will I need regular withdrawals? | Withdrawals may create taxable income or gains |
| Is the product locked in? | Tax-saving products may restrict liquidity |
| How are returns taxed? | Interest, dividends and capital gains can be treated differently |
| Does this fit my goal? | Tax benefits should not override suitability |
Rebalance Without Ignoring Tax Impact
Portfolio rebalancing helps restore your preferred asset allocation.
However, selling appreciated investments can trigger capital gains.
Before rebalancing, investors may consider:
- directing new investments toward underweight asset classes;
- using future SIPs to restore allocation;
- redeeming selectively rather than all at once; and
- reviewing available capital losses before realising gains.
This allows the portfolio to move closer to its target allocation while reducing unnecessary tax events.
Do Not Let Tax Benefits Override Investment Quality
One of the biggest mistakes investors make is choosing a product mainly because it saves tax.
A tax deduction cannot compensate for:
- unsuitable risk;
- weak liquidity;
- poor diversification;
- high costs;
- an inappropriate time horizon; or
- misalignment with financial goals.
The better sequence is:
Goal → Risk → Asset Allocation → Product → Tax Efficiency
Tax planning should support the investment strategy, not replace it.
Tax-Efficient Investing Example
Suppose an investor has ₹2 lakh available for long-term investing.
Instead of choosing a product only because it offers a deduction, the investor first evaluates:
- retirement goals;
- current tax regime;
- existing equity exposure;
- emergency savings;
- risk tolerance; and
- investment horizon.
If the investor is already using the new tax regime and cannot claim a particular deduction, choosing a tax-saving product solely for that benefit may not make sense.
On the other hand, an investor under the old regime who requires long-term equity exposure may find an eligible tax-saving investment more relevant.
The same product can therefore have different value for different investors.
Common Tax-Efficient Investing Mistakes
Investing Only at the End of the Tax Year
Rushed tax-season investing can lead to poor product selection.
Tax planning works better when integrated into your annual financial plan.
Ignoring Post-Tax Returns
A higher pre-tax return does not always mean a better final outcome.
Compare the amount you retain after tax and costs.
Selling Only to Save Tax
Tax-loss harvesting can be useful, but investment fundamentals should remain the primary consideration.
Ignoring Changes in Tax Rules
Tax rates, deductions and holding-period rules can change.
Review the latest rules each year rather than relying on outdated assumptions.
Conclusion
Tax-efficient investing is not about finding a single “tax-free” investment. It is about understanding how taxes interact with your portfolio and making choices that improve your overall post-tax outcome.
Your tax regime, holding period, investment type, capital gains and financial goals all play a role. Strategies such as reducing unnecessary turnover, using eligible deductions appropriately, planning capital gains and losses, and comparing post-tax returns can make your portfolio more efficient.
The objective should always remain the same: build a portfolio that suits your goals first, then structure it as tax-efficiently as possible.